Finseta reports drop in H1 2026 revenues due to macroeconomic headwinds

Finseta plc (LON:FIN), a payments solutions company offering multi-currency accounts to businesses and individuals through its proprietary technology platform, today announced its unaudited interim results for the six months ended 30 June 2026 (“H1 2026”).
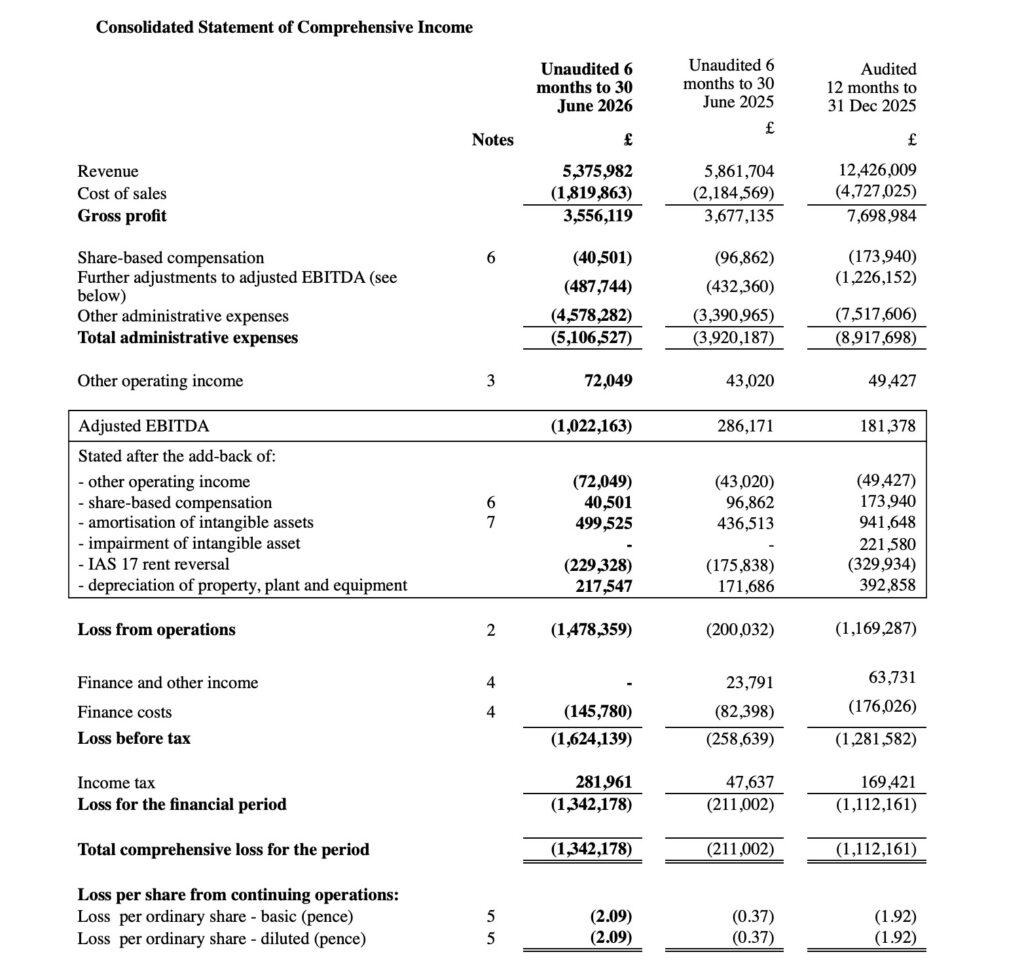
Revenue was £5.4 million (H1 2025: £5.9m) as an increase in the number of active customers was offset by lower average revenue per customer due to macroeconomic headwinds.
Gross margin improved to 66.1% (H1 2025: 62.7%), which reflects several factors including a greater proportion of corporate customer activity in the sales mix and the reduced transaction value per customer coupled with enhancements to the Group’s sales commission structure. The increase in gross margin served to partly mitigate the lower revenue, with gross profit being £3.6m (H1 2025: £3.7m).
Operating expenses were £5.1m in H1 2026 compared with £3.9m for the first half of the previous year. The increase primarily reflects the Group’s ongoing investment in the business to support its strategic initiatives to expand its geographical and market reach, which is expected to lead to accelerated sales growth and increased profitability in the medium term.
Adjusted EBITDA was a loss of £1.0m (H1 2025: £0.3m profit), which is stated after the add-back of other operating income, transaction costs, share-based compensation and non-cash-based accounting adjustments in respect of the Group’s corporate premises. The operating loss was £1.5m (H1 2025: £0.2m loss) and the loss before tax was £1.6m (H1 2025: £0.3m loss) after net finance costs of £0.1m (H1 2025: £0.06m). The reduction reflects the lower revenue and investment in the Group’s strategic initiatives.
The Group recorded a tax credit of £0.3m for H1 2026 compared with £0.05m for the first half of the previous year, resulting in a net loss of £1.3m (H1 2025: £0.2m loss). Basic and diluted loss per share was 2.09 pence (H1 2025: 0.37 pence loss).
As at 30 June 2026, cash and cash equivalents were £2.1m (31 December 2025: £1.5m), with net debt of £0.2m (31 December 2025: £0.3m net debt). This reflects cash generated from financing activities of £1.0m (H1 2025: £0.1m cash used in financing activities), primarily due to the fundraising of £0.9m before expenses as well as a short-term working capital facility secured during the period of £0.5m. Post period end, the Group has repaid £0.25m of this facility. Cash used in operating activities was £0.1m (H1 2025: £0.4m cash generated from operating activities), which primarily reflects the increased loss before tax. Cash used in investing activities was slightly reduced to £0.3m (H1 2025: £0.4m).
The challenging macroeconomic environment has persisted through the summer. In addition, one of the Group’s smaller banking partners withdrew a currency corridor since the H1 2026 period end, which has precluded the Group from servicing customers with that corridor requirement. Whilst there is a strong pipeline from the Group’s strategic focus areas, and an alternative provider for the withdrawn currency corridor is expected to come on stream in Q4 2026, the Group expects H2 2026 revenues to be broadly at the same level as H1 2026, reflecting supressed revenue over the summer months.
The Group continues to expect to deliver a year-on-year improvement in gross margin in line with the H1 2026 outturn. The Group continues to invest in its strategy, whilst maintaining its cost discipline, with costs anticipated to be in line with management’s prior expectations for FY 2026.
The Group’s strategic initiatives are making positive initial contributions, evidenced by the continued success in customer acquisition, and have strengthened Finseta’s position for when the macroeconomic environment improves. Accordingly, the Board remains confident in the Group’s ability to deliver growth and value for shareholders in the medium term.