Marex registers 53% Y/Y jump in Q3 2026 revenues

Diversified global financial services platform Marex Group Limited (NASDAQ:MRX) today reported the Group’s preliminary unaudited financial results for the third quarter of 2026 (‘Q3 2026’).
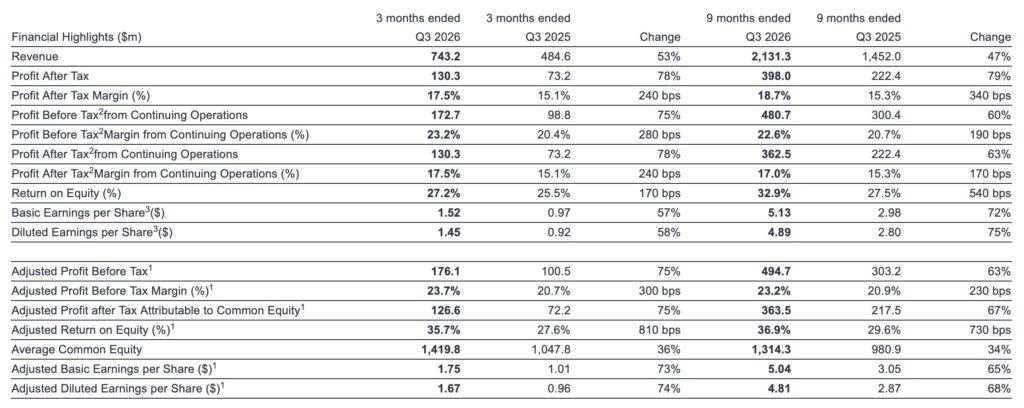
Revenue increased 53% year-on-year to a record $743.2m (Q3 2025: $484.6m), an increase of $47.4m from the previous record quarter in Q2 2026. Year-on-year growth was broad-based across all four business segments, reflecting the continued expansion of the Group’s capabilities, increased client activity and contributions from acquisitions.
Net trading income more than doubled to $420.2m (Q3 2025: $197.7m), driven by Agency and Execution, Market Making and Hedging and Investment Solutions. Agency and Execution delivered continued strong growth in Prime and FX. Market Making delivered strong organic growth, particularly in Metals, supported by favorable market conditions and contributions from recent acquisitions, including Winterflood, Webb Traders and Levmet.
Net commission income increased by $20.4m to $252.6m (Q3 2025: $232.2m), reflecting higher income in Clearing and Agency and Execution. Continued client onboarding and increased activity from existing clients drove growth in Clearing, while growth in Securities within Agency and Execution was partly offset by lower revenue in Energy.
Net physical commodities income increased by $18.5m to $34.7m (Q3 2025: $16.2m), primarily reflecting the contribution from Levmet within Market Making.
Net interest income decreased by $2.8m to $35.7m (Q3 2025: $38.5m) despite significantly higher average balances as the benefit of balance growth was more than offset by higher interest expense.
Interest income grew, reflecting higher average balances of $25.2bn (Q3 2025: $18.6bn) more than offsetting a 60 bps decline in average Fed Funds rates. Higher interest expense associated with the Group’s $500m senior debt issuance, completed in April 2026, together with increased structured note issuance in Hedging and Investment Solutions, more than offset the increase in interest income earned on balances. The Group’s deliberate decision to maintain substantial liquidity headroom creates a modest near-term headwind to net interest income, while strengthening the balance sheet and preserving capacity to support clients and pursue future growth opportunities.
Total expenses increased by $174.3m to $564.2m (Q3 2025: $389.9m), reflecting higher performance-related compensation tied to strong revenue performance, continued investment in technology and infrastructure, and the impact of acquisitions completed since the prior-year period, principally Winterflood, Levmet and Webb Traders.
Compensation and benefits increased by $137.2m to $429.2m (Q3 2025: $292.0m), reflecting higher performance-related compensation and a larger workforce. Average FTE headcount increased by 19% to 3,544 (Q3 2025: 2,968), reflecting acquisitions and continued investment in front office and control and support capabilities.
Profit Before Tax from Continuing Operations increased by $73.9m to $172.7m (Q3 2025: $98.8m), with the margin increasing to 23.2% (Q3 2025: 20.4%). The improvement reflected strong revenue growth across the Group, which more than offset higher performance-related compensation and continued investment in the business.
Profit After Tax increased by $57.1m to $130.3m (Q3 2025: $73.2m), with no contribution from discontinued operations in the quarter.
Adjusting items totaled $3.4m in Q3 2026 (Q3 2025: $1.7m), comprising $2.2m of amortization of acquired brands and customer lists, $0.4m of professional advisory and legal fees in relation to M&A activity and $0.8m of redomiciliation costs.
Adjusted Profit Before Tax increased 75% year-on-year to $176.1m (Q3 2025: $100.5m), while Adjusted Profit Before Tax Margin increased to 23.7% (Q3 2025: 20.7%).
The Board of Directors approved the payment of a dividend of $0.16 per share to be paid on December 2, 2026 to the shareholders on record at the close of business on November 16, 2026.